Entrepreneur
Embedded finance demand is surging. Israeli entrepreneurs explore what’s next
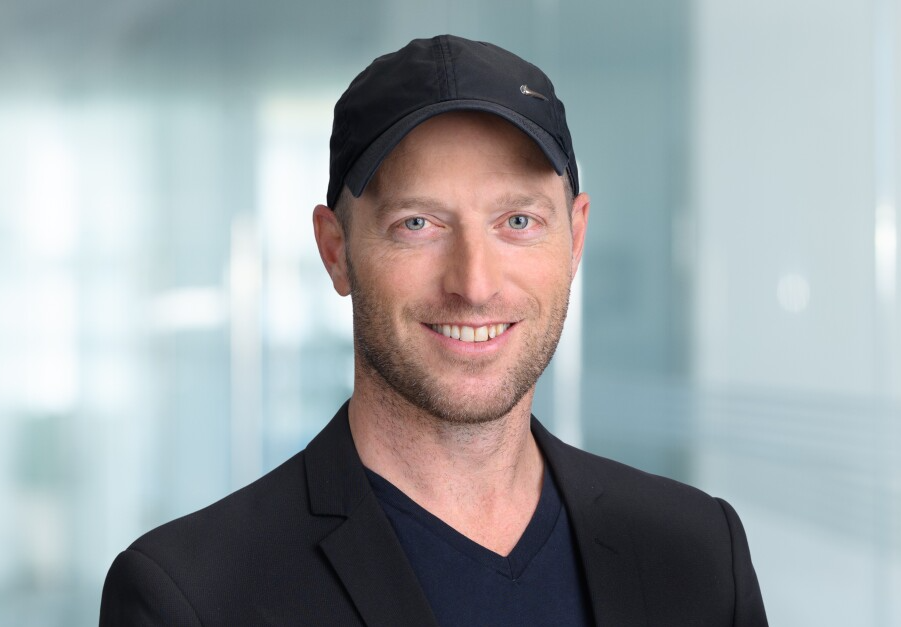
Yaacov Martin (image free for use on a commercial platform in accordance with copyright law, courtesy of Yaacov Martin)
The first half of 2026 has already seen a number of landmark developments in the global fintech space.
First of all, Revolut obtained a full banking license in the UK in March this year. Digital challenger banks have long won out on product innovation. By obtaining full certification, it signals efforts to win an even larger customer base and encroach on the traditional safeholds of legacy banks.
It’s an approach that the company is keen to replicate in other countries, including Israel, where the fintech giant undertakes a new hiring push in efforts to secure a lean bank license.
We can see a similar story playing out with embedded finance. Swedish fintech Klarna, one of the most well-known names in the buy-now-pay-later (BNPL) space for consumers, has built its success on providing payment infrastructure that enables retailers to offer installments as an automatic payment option at checkout. Today, it’s clear that this BNPL behemoth is also encroaching on the territory of credit card providers and other banking services.
In 2026 alone, Klarna partnered with fintech OnePay in the US and launched digital wallets in the UK to make it easier to pay in installments at physical and online stores alike. Although neither of these products are technically a credit card, sitting somewhere between debit and credit, Klarna’s story highlights how much demand there is for embedded finance and flexible payment solutions.
While Klarna no longer has a physical R&D presence in Israel, there is no shortage of fintech innovation on the ground. Here, it’s worth noting that 2025 was an extremely positive year for fintech fundraising: Israeli fintechs raised around $1.4 billion in 2025 and domestic financial technology firms rallied to $5.8 billion.
Established companies are also proving the value of local fintech solutions on the global stage. A prime example of this is Xero’s $3 billion purchase of US-Israeli payment company Melio to expand its reach with small- and medium-sized business accounting teams in the US.
With this significant injection of funds from investors and a growing track record on a global stage, we can expect to see an uptick in activity for Israel’s fintech ecosystem this year that taps into the worldwide momentum and demand for alternative finance solutions and digital product innovation.
Yaacov Martin, CEO and Co-Founder of Jifiti, a fintech company powering embedded financing for banks and financial institutions worldwide, first established the company in Modi’in-Maccabim-Re’ut in 2011. Today, it continues to host major research, development, and operational offices in Modi’in, Israel.
The company’s innovative embedded financing platform enables banks and lenders to seamlessly deploy their consumer and business loan programs at any customer point of need, whether it’s via the bank’s app or website or via third-party channels (online, in-store or via call center). The modular platform provides a fully white-labeled, customizable customer experience, and integrates seamlessly with the bank’s legacy systems.
The last time we spoke with Yaacov, he gave us the inside scoop on Israel’s data protection laws. We caught up with him again to get a better understanding of the latest fintech trends and demand for embedded finance for consumers and businesses alike.
Fintechs keep legacy banks on their toes
For fintechs targeting the banking sector, Revolut is far from alone in its efforts to achieve formal licensing with local financial authorities.
According to Yaacov, this movement has been gaining notable traction globally for the past 18 months and is likely to have important repercussions for the wider banking sector. However, it’s important to understand exactly why fintechs are placing so much emphasis on bank charter applications.
He explained, “This is not fintechs becoming banks. It’s fintechs finishing a job they started years ago – owning the full stack, from the first interaction with a customer through the balance sheet that funds them, with no bank required anywhere in the middle.”
“Revolut is the loudest name in the wave right now, but it is nowhere near the only one – and every lending leader should be paying attention to why this is happening at the same time, all at once,” he continued.
As fintechs continue to encroach on the territory of legacy banks, the pressure is on for these institutions to retain their customer base.
Although the current surge in certification is likely to help fintechs improve their performance with demographics who have typically been more wary of new fintechs, a banking license won’t instantly erase the strong reputational legacy that banks have built over centuries.
“The charter closes the fintechs’ gap. It does not close banks’. Capital, regulatory standing, decades of relationships – banks still hold real advantages a fresh charter doesn’t award a fintech overnight. What banks don’t have is time,” said Yaacov.
For startups in the fintech space, this represents a key opportunity. As fintechs continue to work on trust and authority to win over more consumers, both fintechs and legacy banks are now competing on the frontier of product innovation and founders can cater to both sides.
The result is a growing demand for fintechs that can build the digital infrastructure regulated financial institutions need to compete with, and at the pace of, a fintech.
“The banks that move now – into embedded financing, into the moments where the funding decision actually gets made – keep a seat at the table on their own terms. The ones that wait will be negotiating on a chartered competitor’s terms instead,” he explained.
Why embedded financing isn’t just for consumers
While Klarna may be one of the biggest fintech success stories, the demand for such alternative payment solutions isn’t limited to consumers and ecommerce. Business owners are a growing segment and banks, lenders and fintechs alike are finding new ways to address this gap in the market.
“Banks and lenders realize that embedded financing is not a trend, but a genuine shift in customer expectations that is not going anywhere. If they aren’t in the space, then they risk not only losing out on the growing market, but also losing legitimacy as a payment/banking provider to businesses and consumers alike,” Yaacov explained.
From installment loans and split pay, lines of credit, working capital, asset leasing, and deferred invoice, the edge lies in making the right financing option immediately and seamlessly available to business customers as and when needed, whether that’s via their ordering system, their bank app or in-store at a dealer.
“Whether purchasing wholesale goods or investing in employee training, today’s businesses want — and expect — quick and easy access to finance options at their precise moment of need. Traditional lending channels often cause friction and delays, making for a frustrating customer experience,” he said.
Not only does this demand by businesses help to stimulate direct opportunities for the fintech companies that play in this space, but founders of these companies can also take advantage of these SMB financing options themselves.
“Provisioning financing via digital wallets helps startups and entrepreneurs access funds instantly. This results in faster time to market, streamlined operations and less friction when investing in growth. It also allows businesses to utilize financing directly within the payment tools they already use,” he explained.
A fintech stack in flux
While demand for fintech solutions continues to grow across the entire digital banking spectrum, the approach to technology plays an important role.
For Jifiti, the company’s success has grown from a focus on offering broad, white–label solutions to banks and lenders, but this wasn’t always the case.
Yaacov explained, “Our tech stack has transformed significantly since the early days. From a fairly narrow use case in point-of-sale integrations, we’ve built a scalable, modular end-to-end infrastructure that can support complex financing programs for global banks and lenders across direct-to-customer and embedded channels.”
In order to move beyond retail and cater to a much larger potential share of the market, interoperability and scalability has always been at the core of Jifiti’s product offerings in embedded finance.
“We’ve adopted a fully API-first architecture, built a robust orchestration layer, real-time data analytics, and capabilities to support anything from installment loans and lines of credit to asset leasing and deferred invoice — all configurable and under the bank’s brand.”
“What’s stayed consistent is our focus on interoperability and orchestration, making sure our tech plugs into existing systems and third-party systems with minimal friction,” he said.
Looking ahead, Yaacov was keen to point out that the fintech landscape continues to evolve and companies in the space need to stay ahead of the curve. Jifiti has shown that the product focus at the time of launch isn’t the end game and founders need to continuously innovate. For example, AI is touching every industry at present. For fintech, this represents the potential for disruption and opportunity.
“I think the bigger conversation right now is around how financial institutions can stay relevant in an AI-first world. We’re seeing a shift from traditional product distribution to the exploration of agentic AI distribution — where products need to be discoverable and actionable within AI ecosystems,” Yaacov concluded.
A new chapter for Israel’s fintech ecosystem
Off the back of a solid year of fundraising in 2025, all eyes are on Israel’s fintech ecosystem this year to see how these investments take shape.
The global activity of fintech giants signals that tech innovation continues to create major opportunities by disrupting the legacy status quo and changing how businesses and consumers alike access finance.
As the new digital banking infrastructure continues to evolve and mature, a new generation of borrowers is forming their primary financial relationships, signalling that the reach of fintech solutions is set to grow further. With investor backing, global market demand and a steady pipeline of tech talent, Israel’s fintech sector is primed to capture its share of this shift.
Related Topics