London based entrepreneur, cybersecurity analyst doing a PhD in AI
The Deal with Crypto – Understanding blockchain.
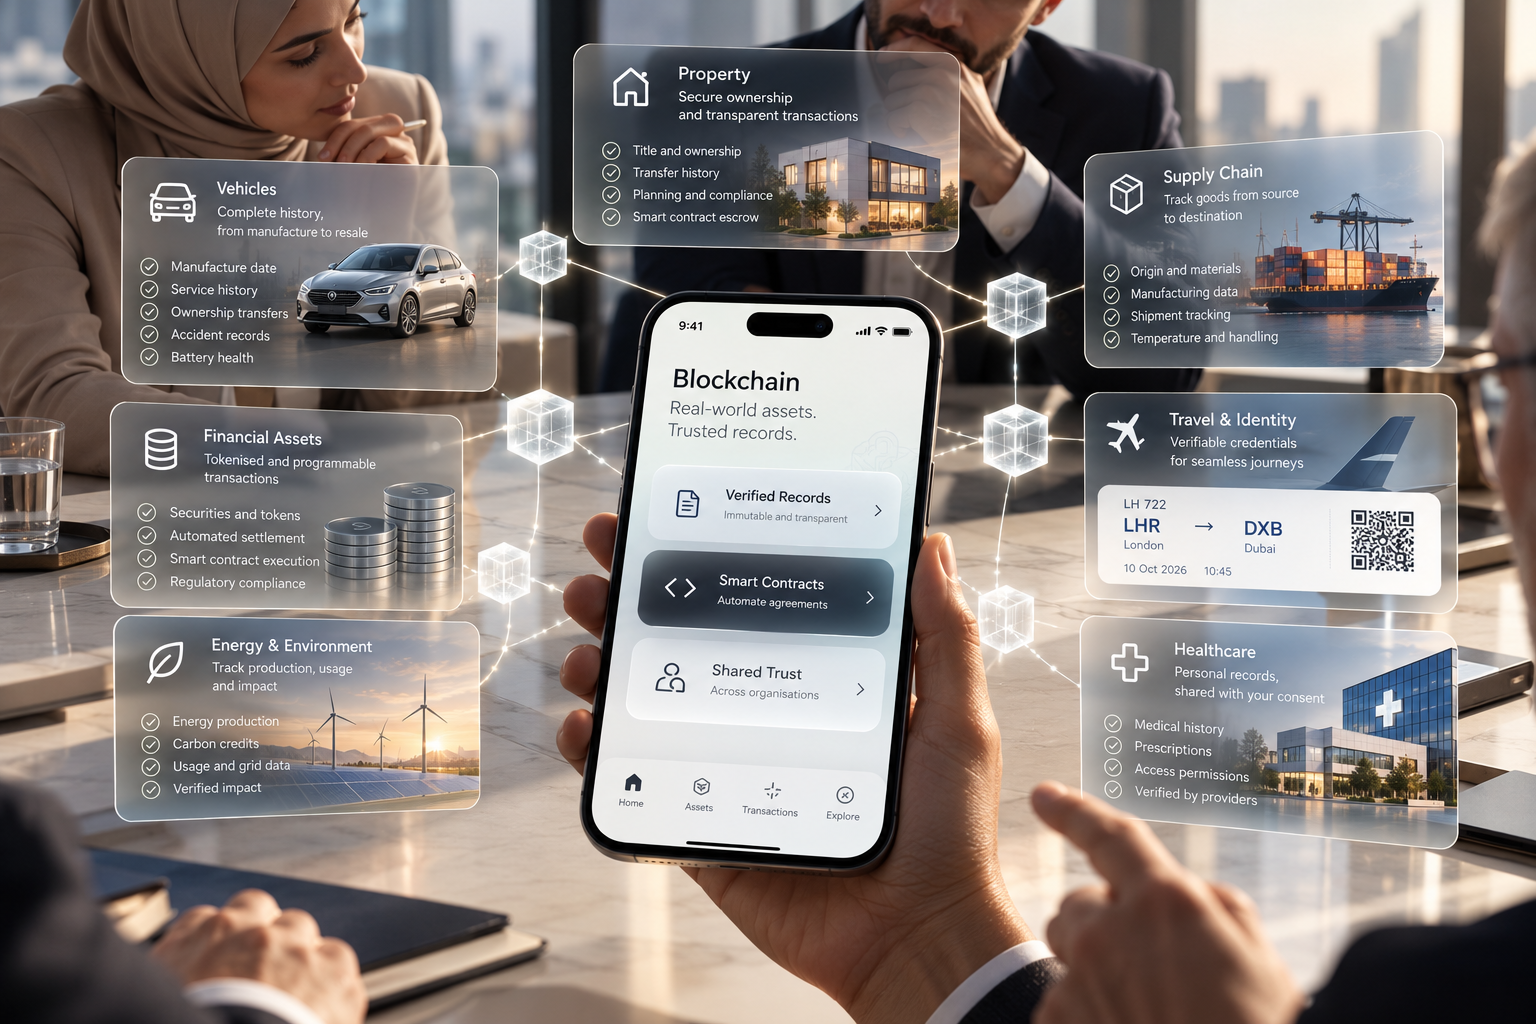
The Deal with Blockchain
Why the future of blockchain may have less to do with cryptocurrencies and more to do with how we establish trust, ownership and accountability.
1. What Exactly Is a Blockchain?
Imagine buying a second-hand car.
The seller tells you the vehicle has travelled 40,000 miles, has never been involved in an accident, and has been serviced regularly.
How do you know whether these claims are true?
You might inspect the service book, contact the manufacturer, check government databases, review inspection records or ask an independent mechanic.
The problem is that the information is fragmented. The manufacturer has one record, the dealership another, the insurance company a third, and the previous owner may possess additional documents.
More importantly, you must trust the accuracy of whoever maintains those records.
Now imagine a shared digital history that records every significant event in that car’s life, with each entry attributable to an authorised party and protected against undetected alteration.
This begins to illustrate the idea behind blockchain.
A conventional database typically has an administrator who can update its contents. A blockchain is a ledger in which records are grouped into blocks, cryptographically linked to earlier blocks, and validated according to agreed rules.
Those records can be replicated across multiple participating computers, making unilateral tampering more difficult.
Consider a simple sequence:
Record A: The car was manufactured on 12 January.
Record B: The vehicle was sold to its first owner.
Record C: The car received its first service at 10,000 miles.
Record D: The battery was replaced at 35,000 miles.
Each new record becomes part of a continually developing history.
The critical innovation is that an earlier record cannot normally be secretly rewritten without disturbing the cryptographic relationships that protect the history.
This does not make every entry true. It makes unauthorised changes more detectable and, depending on the network’s design, much harder to impose.
The US National Institute of Standards and Technology describes blockchain as a distributed, tamper-evident and tamper-resistant ledger.
That is a far more useful starting point than the price of Bitcoin.
2. The Checksum: A Simple Idea with Extraordinary Consequences
At the centre of blockchain is an important mathematical concept: the cryptographic hash.
To understand it, consider a checksum.
When a computer downloads a large file, it may calculate a checksum or hash and compare the result against an expected value. If the values differ, the computer knows something has changed.
A cryptographic hash function takes information and produces a fixed-length digital fingerprint.
Change even a tiny detail in the original information, and the resulting fingerprint will usually be completely different.
A blockchain uses these fingerprints to link blocks together. Each block contains a reference derived from the previous block, creating a chain of cryptographic dependencies.
If someone attempts to alter an earlier transaction, the change disrupts the relevant fingerprints. The alteration becomes apparent to participants verifying the chain.
Cryptographic hashes are considerably stronger than ordinary checksums, because they are specifically designed to make certain forms of manipulation computationally impractical.
But hashing alone is not enough.
The participants must also agree which records are legitimate and in what order they occurred. This is where consensus mechanisms enter the picture.
Bitcoin uses a mechanism called proof of work, which requires miners to perform computational work. Other systems use proof of stake, where validators put economic collateral at risk.
The objective is similar: establish an accepted history without relying entirely on one administrator.
The result is not magical truth. It is a mechanism for producing a shared, verifiable record.
3. What Is a Smart Contract?
A conventional contract is an agreement establishing obligations between parties.
You agree to purchase a house. The seller agrees to transfer ownership. Certain conditions must be fulfilled before payment is released.
Traditionally, solicitors, banks, registries and other intermediaries help verify and execute these obligations.
A smart contract introduces a different possibility.
It is a computer program running on a blockchain that executes predefined rules when specified conditions are satisfied.
Imagine agreeing to pay a supplier £50,000 once a consignment has been delivered and independently verified.
A smart contract could be programmed so that payment is released automatically when an authorised verification arrives.
The logic is straightforward:
If the agreed condition is satisfied, execute the agreed action.
This reduces some administrative work and can make transactions more predictable.
Yet a smart contract is not automatically a legally enforceable contract. Nor can it independently establish whether goods really arrived or were of acceptable quality.
It depends upon reliable information from the outside world, commonly supplied through systems called oracles.
A faulty verification could trigger a perfectly functioning smart contract to release money incorrectly.
That reveals a fundamental limitation: blockchain can secure the execution of rules without guaranteeing the accuracy of the facts on which those rules depend.
4. The Car That Carries Its Own History
Return to our second-hand car.
Imagine every vehicle receiving a persistent digital identity linked to its Vehicle Identification Number, or VIN.
Its associated record might contain manufacturing details, ownership transfers, insurance claims, maintenance work, battery replacements, recalls and inspection results.
Each participating workshop could digitally sign its service entries. Manufacturers, insurers and inspectors could contribute information according to their permissions.
The car would not literally become a block. Rather, it would become an identifiable asset with a chronological series of records, some of which could be verified through a blockchain.
Sensitive documents could remain securely outside the chain, with cryptographic fingerprints stored on it to establish integrity.
When the vehicle changes ownership, its authorised history could accompany it.
A prospective buyer might see that the timing belt was replaced, a damaged panel was repaired, and the odometer readings are consistent.
This is not merely hypothetical. In 2017, Renault announced a blockchain-based digital car maintenance book prototype developed with Microsoft and VISEO.
The broader direction is also emerging through European product-passport requirements. From February 2027, specified categories of batteries, including electric-vehicle batteries, must have digital battery passports containing relevant information about identity, performance, repair and recycling.
Importantly, a digital product passport does not necessarily require blockchain. Other architectures can satisfy the regulatory requirements.
That distinction is essential.
The value is the trusted history, not the presence of blockchain for its own sake.
If the manufacturer controls every record and every participant already trusts the manufacturer, a conventional database might be simpler and cheaper.
Blockchain becomes more interesting when several independent organisations need to contribute to a common history without granting one participant unrestricted control.
5. Supply Chains: From Ownership to Accountability
The same principle applies to supply chains.
Consider a pharmaceutical product.
Its ingredients may originate in one country, undergo processing in another, be packaged in a third, and eventually reach a hospital thousands of miles away.
Every stage introduces questions.
Were the ingredients genuine? Was the product exposed to inappropriate temperatures? Did it pass through an unauthorised distributor? Was a batch substituted?
A shared ledger could provide a verifiable sequence of custody and inspection events.
The same logic applies to food, electronics, aircraft components, precious metals and ethically sourced minerals.
A diamond could have documented provenance. An aircraft component could carry an auditable maintenance history. A battery could have records identifying its materials, service life and recycling route.
For manufacturers and regulators, this might reduce the cost of reconciliation and help identify where responsibility lies when something goes wrong.
However, there is an uncomfortable truth.
If a dishonest supplier falsely claims that a shipment was ethically sourced, blockchain can permanently preserve that false statement.
It cannot independently establish the truth of the claim.
The answer is to combine digital signatures, physical inspections, sensors, independent audits and enforceable accountability.
The ledger protects the record. The surrounding institutions must protect the integrity of the evidence.
6. Why Bitcoin Became So Appealing: The Problem with Fiat Money
To understand why blockchain became associated with money, we need to examine the financial system it appeared to challenge.
Bitcoin was introduced by the pseudonymous Satoshi Nakamoto in a 2008 paper proposing a peer-to-peer electronic cash system.
The timing was significant.
The global financial crisis had exposed profound weaknesses in banks, financial intermediaries and institutional oversight.
Bitcoin proposed a system in which participants could transfer value without requiring a bank to maintain the definitive transaction ledger.
But Bitcoin offered another compelling characteristic: scarcity.
Modern fiat currencies are not backed by fixed quantities of gold. Their value rests on monetary institutions, legal arrangements, economic productivity and public confidence.
Central banks can expand the monetary base, while commercial banks also create deposit money through lending.
These processes are not unconstrained. Excessive monetary expansion can produce inflation, currency depreciation and serious economic instability. Many central banks have institutional independence and price-stability mandates.
Nevertheless, the possibility of expanding the money supply encouraged interest in an alternative whose issuance rules were known in advance.
Bitcoin’s protocol is designed around an eventual limit of approximately 21 million bitcoins.
New bitcoins are introduced through mining rewards, which decline approximately every four years through events known as halvings.
The predetermined scarcity resembles one characteristic of gold: its supply cannot be expanded simply because someone wants more of it.
This created Bitcoin’s image as digital gold.
7. Synthetic Gold: Making Scarcity Computational
Gold is scarce partly because extracting it requires geological discovery, labour, equipment, energy and capital.
Bitcoin reproduces a different kind of difficulty.
Miners compete to find cryptographic solutions satisfying the network’s current difficulty requirements.
The Bitcoin network periodically adjusts this difficulty to maintain an average block production interval of approximately ten minutes.
As competition increases, additional computing power does not automatically produce new bitcoins at a faster aggregate rate. Instead, the competition becomes harder.
The analogy with mining physical gold is intellectually appealing.
Both processes impose costs, both produce an asset with constrained issuance, and both require resources.
But there are important differences.
Gold has physical properties and industrial uses. Bitcoin has no physical substance, and its usefulness depends on its network, acceptability, security and demand.
Furthermore, the energy expended to produce an asset does not establish what that asset is worth.
Bitcoin’s monetary rules are enforced by software and network consensus, not by a law of nature. Changing its supply limit would require sufficiently broad acceptance of different rules.
We can therefore distinguish three propositions.
Bitcoin’s supply is predictably constrained under its present consensus rules.
Its production requires economically costly computational work.
Neither characteristic guarantees that its market price will rise, remain stable or retain purchasing power.
Scarcity may contribute to value, but scarcity alone is not value.
8. Financial Transactions Are One Application, Not the Entire Story
Ironically, blockchain’s most famous application may not ultimately be its most important one.
Finance is a natural candidate because finance depends upon records, ownership, obligations, reconciliation and settlement.
Traditional transactions often involve several institutions maintaining different versions of related information.
A payment or securities transfer may require messaging, verification, clearing, settlement and subsequent reconciliation.
Shared ledger systems could simplify some of these processes by bringing asset ownership and transaction execution into a coordinated environment.
One possibility is the tokenisation of financial assets: representing ownership claims on securities, deposits or other assets through programmable digital records.
Another is the use of appropriately regulated stablecoins or tokenised bank deposits for certain payments.
Smart contracts could coordinate delivery and payment, reducing the possibility that one party transfers an asset while the other fails to pay.
These are precisely the possibilities being examined by central banks and financial institutions.
The Bank for International Settlements, in its June 2026 assessment, recognised the potential of tokenisation to improve financial infrastructure while warning about weaknesses in current stablecoin arrangements.
But there are trade-offs.
Public blockchains may experience congestion, transaction fees and scalability constraints. Permissioned networks may improve performance but sacrifice some decentralisation.
And merely placing a traditional financial instrument on a blockchain does not remove the need for legal ownership rights, liquidity, supervision or dispute resolution.
A better technological record cannot repair a fundamentally unsound financial product.
9. The Fraud Problem: When Irreversibility Meets Human Psychology
Perhaps the greatest obstacle to broader cryptocurrency adoption is not cryptography.
It is human behaviour.
People are vulnerable to authority, urgency, imitation, fear and the promise of extraordinary returns.
Fraudsters understand this remarkably well.
Imagine discovering a problem with your cryptocurrency account.
You search for help on X, formerly Twitter, and encounter an account resembling the exchange’s official support service.
It has a professional-looking logo, similar branding and a convincing explanation.
The supposed representative tells you that your funds are at immediate risk and instructs you to connect your wallet to a website, enter recovery information or authorise a protective transfer.
In reality, the account belongs to a criminal.
The fraudster is not defeating the blockchain’s cryptography. The fraudster is persuading the user to perform the attacker’s desired action.
The same pattern appears in phishing emails, impersonated executives, fraudulent investment groups, romance scams and fabricated recovery services.
The FBI specifically warns about criminals impersonating cryptocurrency-exchange employees and using account-security stories to steal funds.
Its 2025 Internet Crime Report, released in April 2026, recorded more than $11 billion in reported losses associated with cryptocurrency-related complaints in the United States.
This figure covers a range of cryptocurrency-related crimes; it is not evidence that blockchain protocols themselves caused every loss.
But it highlights an enormous consumer-protection challenge.
Many confirmed blockchain transfers cannot simply be cancelled by calling a bank.
The network may have executed the transaction exactly as instructed, even when the instruction resulted from deception.
A perfectly valid transaction can therefore represent a profoundly illegitimate human outcome.
This is an important distinction between technical validity and informed consent.
Cryptocurrency systems have sometimes transferred substantial operational responsibility from financial institutions onto ordinary individuals, without giving those individuals the knowledge, protections or support structures needed to bear that responsibility.
10. From Unregulated Markets to Accountable Infrastructure
It would be inaccurate to describe all cryptocurrency activity in 2026 as unregulated.
Regulatory approaches vary across countries, assets and intermediaries.
The European Union’s Markets in Crypto-Assets Regulation, or MiCA, established rules covering significant categories of cryptoasset issuers and service providers. The final EU transitional period for relevant providers expired in July 2026.
The direction is towards greater accountability, not complete regulatory absence.
However, regulation of a cryptocurrency exchange does not automatically make every token traded through it a sound investment.
Nor does it prevent someone from creating a fake support account, operating from another jurisdiction or persuading victims to use unlicensed services.
The problem is therefore broader than financial regulation.
It requires reliable identity verification, clear transaction disclosures, consumer education, fraud monitoring, enforceable sanctions and meaningful avenues for investigation.
Public blockchains can sometimes assist law enforcement because transactions leave observable trails. They are often pseudonymous rather than completely anonymous.
But following funds is not always equivalent to recovering them.
The greatest practical innovation may consequently involve making blockchain transactions safer before they are finalised.
A system that clearly explains what a wallet signature authorises, warns about suspicious counterparties and provides appropriate fraud controls could have more social value than another speculative token.
11. What Will Blockchain Ultimately Be Useful For?
We can now answer the question more objectively.
Blockchain is especially interesting when several independent parties must maintain a shared history; when ownership or custody changes hands; when auditability matters; when records must be resistant to retrospective alteration; and when programmable execution can reduce unnecessary reconciliation.
But blockchain is not inherently superior to every conventional database.
Where one trustworthy institution controls the process, a well-designed centralised system may be faster, cheaper, easier to update and better suited to protecting personal information.
There are also legitimate reasons to amend or erase certain data. Permanent public recording can conflict with privacy and correction requirements.
The practical choice should therefore depend on the problem.
We should ask whether participants genuinely need shared control; whether cryptographic verification provides a meaningful advantage; whether input information can be trusted; whether performance and privacy requirements can be met; and whether the benefits justify the cost.
If a conventional database satisfies those requirements more effectively, using blockchain may add complexity rather than value.
The most successful implementations may not involve public cryptocurrencies at all. They may be permissioned systems shared between institutions, or hybrid architectures that combine conventional databases with digital signatures and verifiable ledger records.
And that is entirely acceptable.
Blockchain Must Become Useful Enough to Be Invisible
The central idea of blockchain is more interesting than much of the industry built around it.
Its original promise was to allow participants to maintain and verify a shared history without depending entirely on a single authority.
A blockchain cannot establish the honesty of the person supplying information. A smart contract cannot guarantee that its conditions are morally or legally fair. And a scarce digital asset cannot guarantee economic value simply because it is difficult to produce.
Yet the underlying technology offers something potentially important: a way of reducing disputes about what was recorded, when it was recorded, and which authorised party recorded it.
Imagine buying a used car and receiving a dependable maintenance history without needing to understand cryptographic hashes.
Imagine identifying the origin of a defective aircraft component without reconciling dozens of conflicting databases.
Imagine moving a financial asset between institutions without repeated manual verification.
The consumer need not know whether any of these services uses blockchain.
They need the system to be dependable, understandable and secure.
That is the likely destination of the technology: not replacing every institution, not eliminating the necessity of trust, and certainly not turning every digital token into an investment.
Instead, blockchain may become one of several tools for making trust more verifiable and accountability easier to establish.
The ultimate success of blockchain will not be measured by how many people speculate on its coins, but by how many important processes become more reliable because the technology is there.
And perhaps the greatest indication of its maturity will come when people no longer need to talk about blockchain at all.
Related Topics
Related Posts