Thinking about 'Resilient Zionism'
Why Missed Climate Targets by Global Investors Matter for Israel
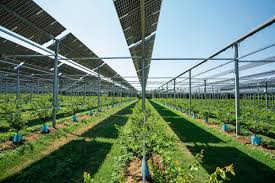
The recent acknowledgment by Temasek, one of the world’s leading state-owned investment companies, that it is likely to miss its 2030 portfolio decarbonization target is an important signal. The issue is not necessarily lack of ambition by global investors to reduce its environmental footprint, it is the difficulty of aligning climate roadmaps with real-world economics: technology readiness, infrastructure timelines, sector cost curves, policy incentives and the ability of portfolio companies to finance climate-transition capex.
This is the challenge facing many of the world’s largest investment holding companies, sovereign investors and asset owners.
A 2050 net-zero pledge is no longer enough. Stakeholders, including regulators, increasingly want credible interim targets, sector-specific transition plans, financed-emissions reporting (a measure of how much greenhouse gas emissions an investor effectively finances through its capital deployment) and evidence that climate commitments are shaping actual allocation decisions.
For investment companies, the core question surrounding climate commitments is whether capital is being allocated toward economically grounded transition pathways that can compound financial value while reducing emissions over time.
This is where Israel becomes relevant — and not abstractly. Temasek itself holds positions in Israeli technology and agritech companies, meaning the gap between its decarbonization targets and its portfolio reality runs, in part, through Israel’s innovation economy.
Israel is not a major source of global emissions, nor a central actor in global climate negotiations, however it is deeply embedded in the value chains of many global conglomerates — through R&D centers, software platforms, mobility systems, food-tech, health-tech, climate-tech and advanced manufacturing partnerships.
In other words, Israel is increasingly part of the Scope 3 reality of global companies. (Scope 3 refers to the indirect greenhouse gas emissions that occur across a company’s value chain — from its suppliers, partners and the products it enables — and which typically dwarf the emissions a company produces directly). When a European automotive group for example relies on Israeli software for its autonomous driving stack, or a global agri-business sources precision irrigation technology developed and managed in Israel, the emissions profile of those value chains — and the transition risk embedded in them — runs through Israel.
As investors move beyond headline climate pledges and examine the real operational pathways of their portfolio companies, Israel’s relevance grows — both as a source of transition risk and as a source of transition solutions.
That creates an opportunity for Israel’s latent sustainable finance market to position itself as a bridge between global capital and executable decarbonization. Not only by funding climate-tech innovation, but by financing deployment across the real economy: energy infrastructure, industrial processes, and data management — the unglamorous but essential architecture of any credible transition.
The next phase of sustainable finance will not be defined by who makes the boldest pledge, but by who builds the most credible, investable and economically grounded transition roadmap.
Israel has a role to play in making those roadmaps executable.
Related Topics
Related Posts