Aliyah Adviser
The Quiet Half of Aliyah: The Kaplans’ Story
(Gemini Generated Images)
The Quiet Half of Aliyah: What the Kaplans Didn’t Know to Ask
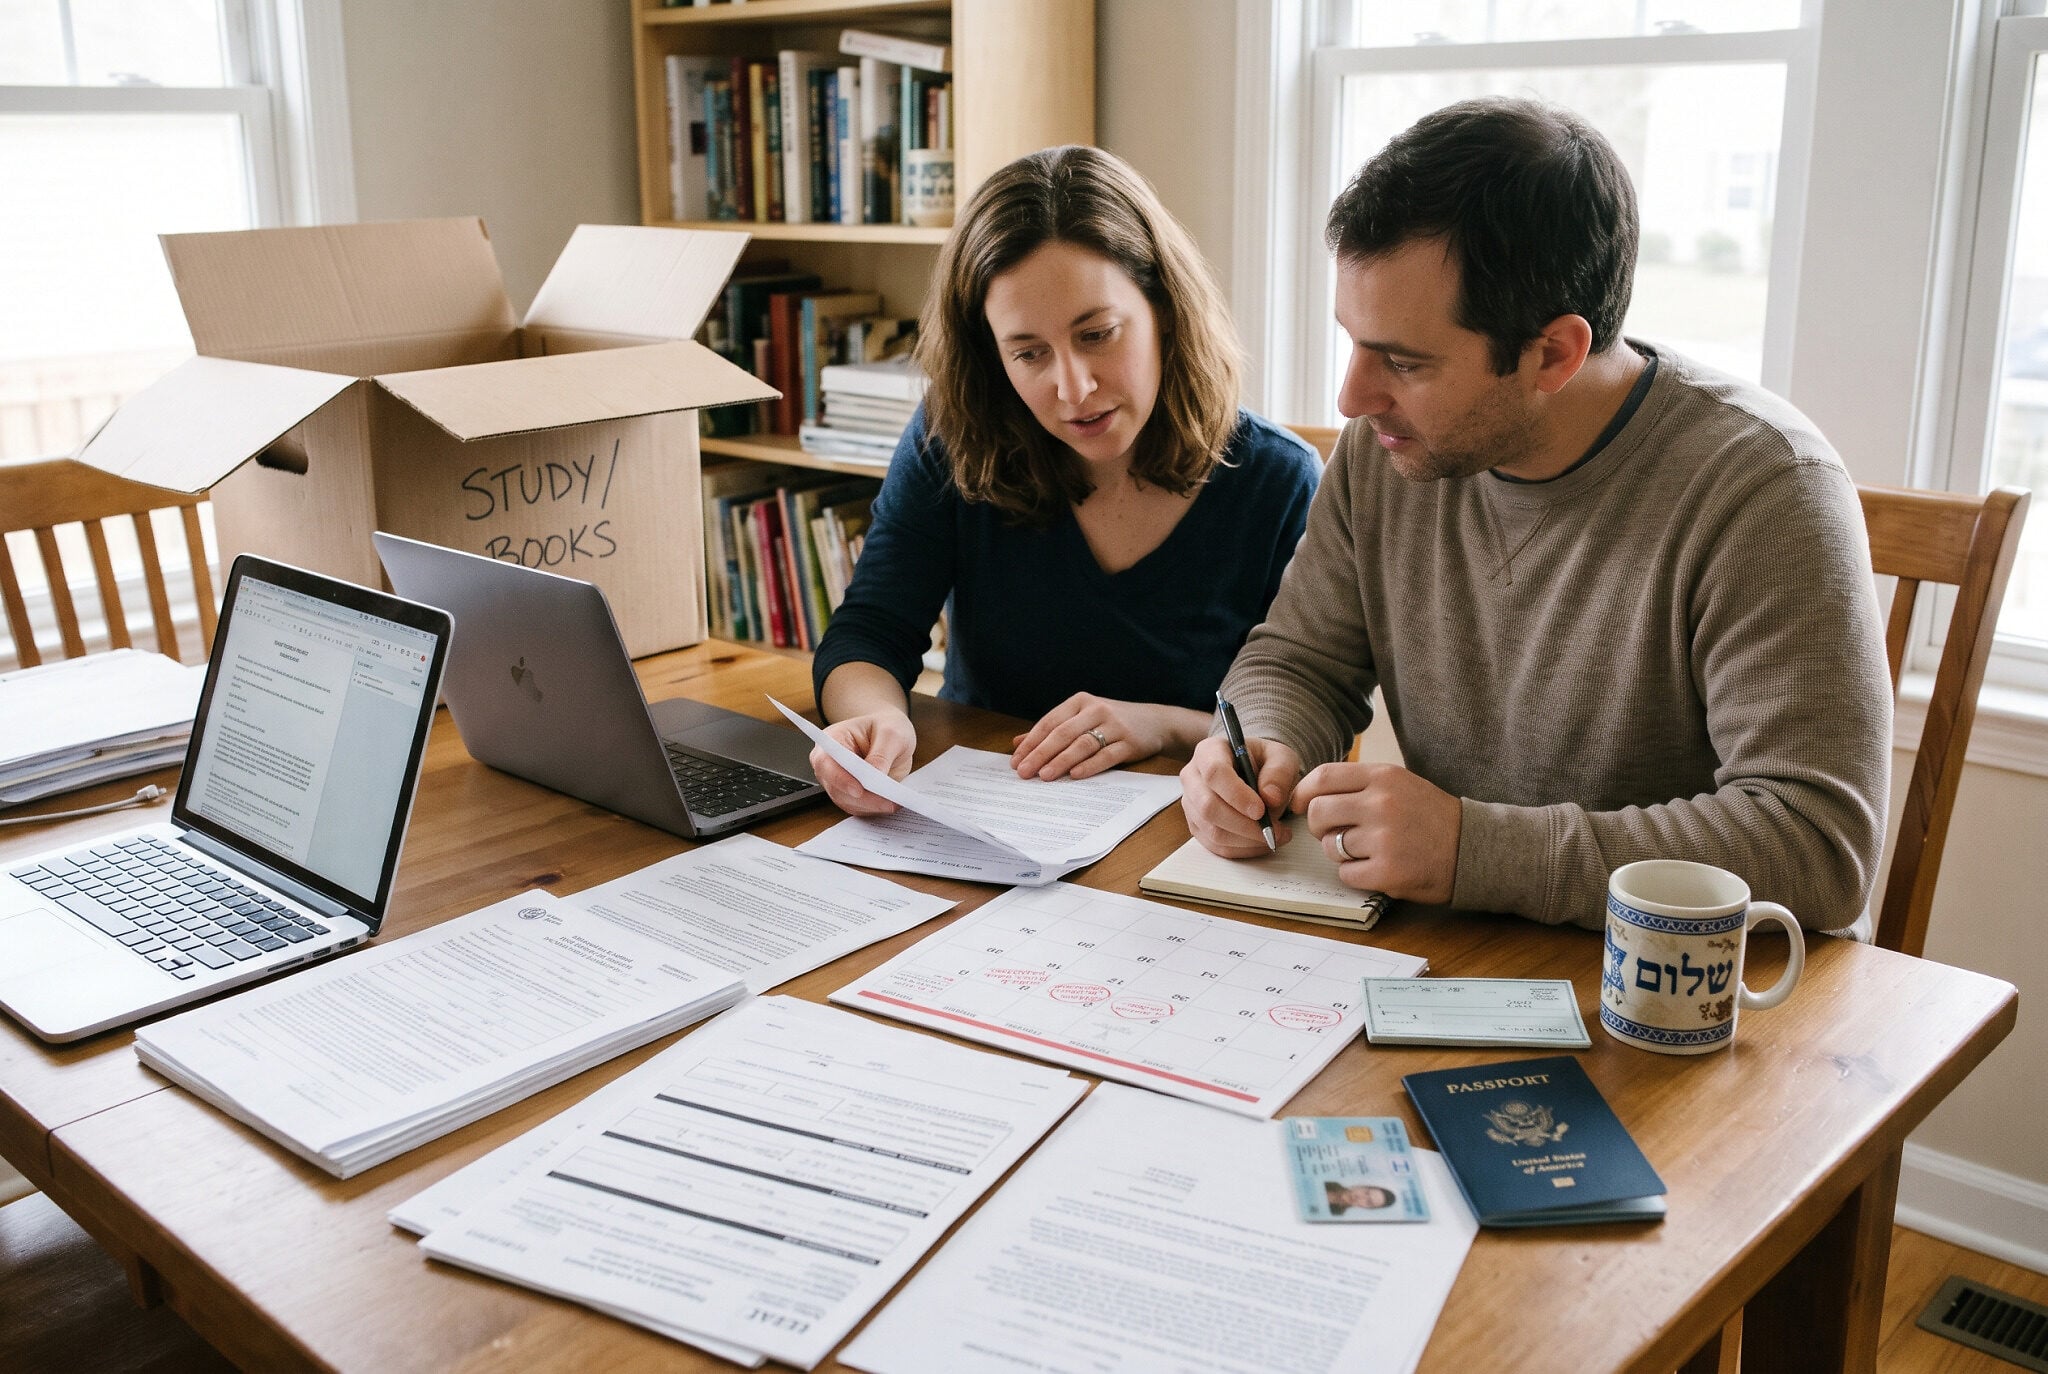
Picture a family. Let’s call them the Kaplans: two parents, three kids, a house in New Jersey, a 401(k), a modest investment account, and an aliyah date circled on the calendar. For a year, their kitchen-table conversations have been about the visible half of aliyah. Modiin or Ra’anana? Which school? How many bedrooms can we afford?
Those questions matter. But in my work with olim, I’ve come to think of them as the easy half. The other half is quieter: dates, definitions, forms and sequences that nobody posts photos of in the Facebook groups. That half is usually where the expensive surprises live. So let’s walk the Kaplans through it.
- The day they land is not “The Day”
The Kaplans assume their new life begins the moment the plane touches down at Ben Gurion. Emotionally, it does. Legally, there are several different clocks.
For Israeli tax purposes, residency is generally determined by where your “center of life” is: your family, your permanent home, your work, your economic and social ties. It is not simply your landing date or the date on your Teudat Oleh. There is also a rebuttable presumption based on days in the country: 183 days or more in a tax year, or at least 30 days in that year plus 425 or more over that year and the two before it.
The Teudat Oleh itself has its own timing. First-time olim arriving on an aliyah flight usually receive it at the airport. Others, such as people who first came on an A-1 visa or some split-aliyah spouses, often receive it at a later appointment. If your dates don’t line up neatly, that is a real question, and the time to ask it is before you book the flight.
2. The reform everyone is talking about
Israel has long offered new immigrants a 10-year exemption on foreign-source income, which can include foreign pensions, capital gains on foreign assets and ongoing income from abroad. In 2026 a temporary provision added something new. Under the Tax Authority’s current guidance, olim and veteran returning residents who became Israeli residents between 5 November 2025 and 10 February 2027 may be exempt on Israeli salary and business income, up to annual caps that change year by year through 2030. Note the wording: “became Israeli residents.” Sources have not been fully consistent about the end date of that window, which is one more reason to confirm your own situation with a licensed Israeli CPA rather than a forum thread.
3. When the money moves matters too
Here’s a detail the Kaplans almost missed. Under certain conditions, interest on a foreign-currency deposit in an Israeli bank may be exempt for 20 years. As far as I know, the conditions include that the money was held abroad before becoming a resident, that it is deposited within 90 days of the transfer, and that the deposit is held for at least three months. In other words, how and when they bring their savings over is not just a logistics question.
It also helps to know that married olim generally open a joint Israeli bank account, and both spouses need to be there in person, because the sal klita, the absorption basket, is paid into it. One missing spouse can mean a second trip to the bank.
4. The house in New Jersey is still in the story
The Kaplans thought of the house, the 401(k) and the brokerage account as “back there.” But for US citizens, back there never fully goes away. The US taxes its citizens on worldwide income wherever they live, so the Kaplans will keep filing US returns. Once their combined foreign accounts exceed $10,000 at any point in the year, and that includes their new Israeli accounts, they will generally need to file an FBAR, even if those accounts earn nothing. Other forms may apply as well.
Whether to keep, rent out or sell the house, and how the 401(k) is treated, are questions for a US-licensed professional working alongside an Israeli one. Olim from the UK and elsewhere face their own versions of this. The details differ, but the principle holds: obligations in the country you left may continue.
5. Health insurance has its own clock
As first-time olim, the Kaplans are generally registered with a kupat cholim at the airport and are exempt from the health waiting period. Their neighbors’ story is different. Picture an Israeli couple who lived in Boston for eight years and are now coming home. Returning residents who were abroad for a long stretch, and didn’t keep paying health insurance, can face a waiting period of one month for each year abroad, with a minimum of two and a maximum of six. National Insurance allows that wait to be redeemed with a one-time payment, which can be made from abroad. That is worth settling before the lift, not after the first doctor’s visit.
6. The first year deserves its own budget
The sal klita helps with living expenses during roughly the first six months, including rent. Part is paid at the airport and the rest in monthly deposits. Even so, the first year usually costs more than the “steady state” budget most families build: deposits, furniture, transport, and the gap before income settles. A separate first-year cash-flow plan is one of the most stress-reducing documents a family can make.
7. Order matters more than speed
Some things can only be done abroad, and they take time:
- Passports valid for at least a year after aliyah
- Apostilled long-form birth certificates (a hospital certificate isn’t enough)
- Apostilled civil marriage certificates (a ketubah isn’t enough)
- For many North Americans, a personal-status affidavit that must still be valid on aliyah day
Some happen at the airport: the Teudat Oleh, a temporary Teudat Zehut, kupat cholim registration and the first sal klita payment. And some belong to the first 90 days: the bank, the biometric Teudat Zehut, the local Ministry of Aliyah office, ulpan and school registration.
In a shorter version, If the Kaplans kept one page on the fridge, it would say:
- Confirm when you actually become a tax resident, before you book the flight.
- Understand which exemptions apply to you, and their exact conditions.
- Plan when and how your savings move.
- Map what stays abroad, and what you’ll still report there.
- Check your health-insurance clock, especially as a returning resident.
- Build a separate first-year budget.
- Get your documents apostilled early.
None of this is meant to make aliyah sound harder than it is. Many families have done it, and most will tell you it was one of the best decisions of their lives. My point is simply that the quiet half deserves as much attention as the neighborhood. Before you choose the street, build a roadmap. Modiin will still be there.
This article is general information, not tax or legal advice. Tax questions should be reviewed with a licensed Israeli CPA, and with a professional in your country of origin.
Related Topics